Showing posts with label Eurogeddon. Show all posts

Thursday, October 8, 2015

Video - UKIP Leader Nigel Farage threatening with Britex, We're living in a German-dominated Europe of Disharmony.

Saturday, October 25, 2014

Great Britain closer to quitting EU.


Great Britain closer to quitting EU. (Express). By: Macer Hall

FURIOUS David Cameron last night conceded that Britain had been pushed closer to a European Union exit after receiving an eye-watering £1.7 billion Brussels bill.

Red-faced with anger, the Prime Minister vowed to block payment of the “completely unacceptable” surcharge presented by EU officials in a surprise overhaul of national contributions.

“It is not acceptable, it is an appalling way to behave,” Mr Cameron said.

Calls for the UK to withdraw from the EU intensified yesterday following the cash demand, which will cost every family in the country £65.

And he admitted the latest insult to UK taxpayers – with the bill due to be paid by December 1st – was undermining his drive to keep Britain in the EU.

When pressed on the issue by the Daily Express he said: “It certainly doesn’t help, put it that way.”


Mr Cameron insisted: “It is an unacceptable way for this organisation to work, to suddenly present a bill like this for such a vast sum of money with so little time to pay it.

And it is an unacceptable way to treat one of the biggest contributors to the European Union.”

Repeatedly thumping his lectern with a clenched fist, he added: “I am not paying that bill on December 1st.
"If people think I am, they’ve got another thing coming; it is not going to happen.
“As an important contributor to this organisation, we are not suddenly going to get out our chequebook and write a cheque for two billion euros; it is not happening.”

As the row deepened, there was fresh pressure for the Prime Minister to accelerate his promised in-or-out referendum on Britain’s EU membership.

UK Independence Party leader Nigel Farage warned that Mr Cameron was in “real political trouble”.
Yes, it’s outrageous, but that’s how the European Union works,” he said.
He’s in a very weak position. He can do nothing about this."
And I think, really, he’s now being pushed into a position where, unless he brings forward his referendum promise, I think he’s in real political trouble.” More here.

RELATED:  'Euro Communism' 101 - New Law against Democratically Dismantling EU from Within.

Thursday, October 23, 2014

'Euro Communism' 101 - New Law against Democratically Dismantling EU from Within.


'Euro Communism' 101 - New Law against Democratically Dismantling EU from Within. HT: GatestoneInstitute.
It looks as if this new law is meant to serve as a severe roadblock to parties that would like to dismantle the EU in a democratic and peaceful way from within.
A rather dull semantic trick pro-EU figures usually apply, is calling their opponents "anti-Europe."
Two years ago the European Commission proposed a law that would authorize an “independent authority” within the European Parliament [EP] to decide whether EP parties would receive an official legal status as EP parties. 

This legal status is needed for a party to obtain EP party subsidy, which is designed to cover 85% of party expenditures.


Despite a British and Dutch lobby against the law, it was passed by the EP on September 29, 2014.

Among the demands parties have to meet are that of “internal party democracy” and that they must “respect the values on which the European Union is based.” Among these values are: “pluralism, non-discrimination, tolerance, justice, solidarity and equality between women and men.” Also, the parties must be active in at least seven out of 28 EU member state countries.

The law states that: “decisions regarding a party’s respect for values on which the EU is based, may only be taken following a special procedure and in cooperation with a committee of independent prominent individuals.”

Although the law does not specify the composition of this illustrious special committee, it is highly probable that Martin Schulz, the EP’s chairman, is among them

Schulz is a German socialist who got reelected as EP chairman even though he was absent during the parliamentary debate for the position. Schulz is also known for strongly condemning the content and distribution of a film critical of Islam, “Innocence of Muslims,” and for hisdisproportionate criticism of Israel.

Even though the committee is designated as an “independent authority,” within the self-aggrandizing dynamic of the EU, one cannot be “prominent” and “independent” at the same time.

Therefore, prominent individuals within the EU are those that fully and without any reticence subscribe to the EU’s mission of dismantling European nation states and furthering the EU’s influence at the cost of national democracies. More here.

Wednesday, October 8, 2014

Greece: unpaid electrical bills amount to 1.7 billion euros, 2.16 Billion $


Greece: unpaid electrical bills amount to 1.7 billion euros, 2.16 Billion $. (Ansamed)

As of the end of June, the Greek public power company DEI is owed about 1.7 billion euros, which it intends to claim back through the courts as daily To Vima online reports today.

Prior to the introduction of the special tax on electrified real estate (Eetide) in 2012, unpaid electrical bills amounted to less than 300 million euros.

As a result though many customers were unable to pay the tax and ended up not paying their electricity bills at all. Even though the government later tried to improve the tax, customers were still unable to pay as necessary. Based on DEI's data, unpaid bills amounted to 1.4 billion euros at the start of the year and increased to 1.7 billion by the end of June.

About 950 million euros is attributed to households, 430 million euros to high voltage users and a further 180 million euros is owed by the greater public sector.

At this rate, the power company has estimated that unpaid bills will amount to 2 billion euros by the end of the year. In order to curb this increase, DEI has assigned the collection of 20,000 unpaid bills to experienced legal service providers. Hmmmm.....Good luck, as the saying go's 'You can't skin a stone' (ANSAmed).

Friday, February 14, 2014

Europe Considers Wholesale Savings Confiscation, Enforced Redistribution.


Europe Considers Wholesale Savings Confiscation, Enforced Redistribution.HT: ZeroHedge.
At first we thought Reuters had been punk'd in its article titled "EU executive sees personal savings used to plug long-term financing gap" which disclosed the latest leaked proposal by the European Commission, but after several hours without a retraction, we realized that the story is sadly true
Sadly, because everything that we warned about in "There May Be Only Painful Ways Out Of The Crisis" back in September of 2011, and everything that the depositors and citizens of Cyprus had to live through, seems on the verge of going continental.

In a nutshell, and in Reuters' own words, "the savings of the European Union's 500 million citizens could be used to fund long-term investments to boost the economy and help plug the gap left by banks since the financial crisis, an EU document says."
What is left unsaid is that the "usage" will be on a purely involuntary basis, at the discretion of the "union", and can thus best be described as confiscation.
The source of this stunner is a document seen be Reuters, which describes how the EU is looking for ways to "wean" the 28-country bloc from its heavy reliance on bank financing and find other means of funding small companies, infrastructure projects and other investment.

So as Europe finally admits that the ECB has failed to unclog its broken monetary pipelines for the past five years - something we highlight every month (most recently in No Waking From Draghi's Monetary Nightmare: Eurozone Credit Creation Tumbles To New All Time Low), the commissions report finally admits that "the economic and financial crisis has impaired the ability of the financial sector to channel funds to the real economy, in particular long-term investment."

The solution? "The Commission will ask the bloc's insurance watchdog in the second half of this year for advice on a possible draft law "to mobilize more personal pension savings for long-term financing", the document said."
Mobilize, once again, is a more palatable word than, say, confiscate.
And yet this is precisely what Europe is contemplating:
Banks have complained they are hindered from lending to the economy by post-crisis rules forcing them to hold much larger safety cushions of capital and liquidity.

The document said the "appropriateness" of the EU capital and liquidity rules for long-term financing will be reviewed over the next two years, a process likely to be scrutinized in the United States and elsewhere to head off any risk of EU banks gaining an unfair advantage.
But wait: there's more!

Inspired by the recently introduced "no risk, guaranteed return" collectivized savings instrument in the US better known as MyRA, Europe will also complete a study by the end of this year on the feasibility of introducing an EU savings account, open to individuals whose funds could be pooled and invested in small companies.
Because when corporations refuse to invest money in Capex, who will invest? Why you, dear Europeans. Whether you like it or not.
But wait, there is still more!
Additionally, Europe is seeking to restore the primary reason why Europe's banks are as insolvent as they are: securitizations, which the persuasive salesmen and sexy saleswomen of Goldman et al sold to idiot European bankers, who in turn invested the money or widows and orphans only to see all of it disappear.
It is also seeking to revive the securitization market, which pools loans like mortgages into bonds that banks can sell to raise funding for themselves or companies. The market was tarnished by the financial crisis when bonds linked to U.S. home loans began defaulting in 2007, sparking the broader global markets meltdown over the ensuing two years.

The document says the Commission will "take into account possible future increases in the liquidity of a number of securitization products" when it comes to finalizing a new rule on what assets banks can place in their new liquidity buffers. This signals a possible loosening of the definition of eligible assets from the bloc's banking watchdog.
Because there is nothing quite like securitizing feta cheese-backed securities and selling it to a whole new batch of widows and orphans.
And topping it all off is a proposal to address a global change in accounting principles that will make sure that an accurate representation of any bank's balance sheet becomes a distant memory:
More controversially, the Commission will consider whether the use of fair value or pricing assets at the going rate in a new globally agreed accounting rule "is appropriate, in particular regarding long-term investing business models".
To summarize: forced savings "mobilization", the introduction of a collective and involuntary CapEx funding "savings" account, the return and expansion of securitization, and finally, tying it all together, is a change to accounting rules that will make the entire inevitable catastrophe smells like roses until it all comes crashing down.
So, aside from all this, Europe is "fixed."

The only remaining question is: why leak this now? Perhaps it's simply because the reallocation of "cash on the savings account sidelines" in the aftermath of the Cyprus deposit confiscation, into risk assets was not foreceful enough? What better way to give it a much needed boost than to leak that everyone's cash savings are suddenly fair game in Europe's next great wealth redistribution strategy.

Update:

First It Was Bail-Ins And Now EU Sees “Personal Pension Savings” As “Plug” For Banks

An objective stress test of the euro zone's biggest banks could reveal a capital shortfall of a whopping  770 billion euros (more than $1 trillion), a study by an advisor to the EU's financial risk watchdog and a Berlin academic has found.

Related:

Some European banks 'have no future', need to 'die in an orderly fashion’– new bank supervisor


Monday, February 10, 2014

Some European banks 'have no future', need to 'die in an orderly fashion’– new bank supervisor


Some European banks 'have no future', need to 'die in an orderly fashion’– new bank supervisor. (RT).

“We have to accept that some banks have no future,” Nouy told the Financial Times (FT) in an interview published February 10, 2014. Nouy will serve a five-year term.

The single supervisory mechanism (SSM) is a regulatory body of the EBC that along with the London-based European Banking Authority, will conduct an asset quality review, and the health of 130 banks that hold about 80 percent of all bank assets in the 18-member currency bloc.

The mega-regulator will either close "non-viable" banks and attempt to re-capitalize weak, yet "viable" lending institutions by November 2014, when they take over as the region’s bank regulator and announce the results of the "stress tests".

I hope that we will be able to resolve to put banks in run-off and not necessarily try to combine bad banks with good banks, Nouy said.

I do not have any idea of how many banks have to fail. What I know is that we want to have the highest level of quality,” she told FT.

The ECB will assess a lender’s key risks, including liquidity, leverage and funding, as well as asset quality and the ability of a banks’ balance sheet to resist stress scenarios.
They may need resolution plans because they have to die in an orderly fashion; that’s very important for financial stability, Nouy said.
The French national was appointed to chair the ECB Supervisory Board in December after a long stint at the Bank of France.

We have to let some banks disappear in an orderly fashion, and not necessarily try to merge them with other institutions. We don’t want banks disappearing in a disorderly fashion, that’s the main point.
Nouy’s message is in step with Mario Draghi, who has previously said some banks need to fail in order for the health check to be legitimate. The tests in 2011 were widely seen as unsuccessful because lenders hugely underestimated their risks.

“If they do have to fail, they have to fail. There’s no question about that,” Draghi said in October.


Eurozone banks may have a capital deficiency of as much as €50 billion, according to Davide Serra, chief executive of London-based Algebris, an investment firm that specializes in government and banking consulting. Serra told The Telegraph that Germany has one of “the worst banking systems in the world”, and also expects many banks in Portugal and Greece to be low on capital. Read the full story here.

Friday, February 7, 2014

'Brace For Impact' - Germany says European Central Bank’s quantitative easing illegal


'Brace For Impact' - Germany says European Central Bank’s quantitative easing illegal.(RT).

Germany’s constitutional court said the European Central Bank’s bond-buying program- Outright Monetary Transaction (OMT) - “infringes” on the powers of individual nations, a claim the ECB has flatly denied.
The OMT program was launched in response to the European debt crisis in September 2012 under ECB President Mario Draghi, and is credited with helping the flagging euro currency make a market comeback. Under the program the Governing Council of the ECB buys in secondary, sovereign bond markets the obligations issued by Eurozone members.
In the view of the Senate, there are important reasons to assume that it exceeds the European Central Bank’s monetary policy mandate and thus infringes the powers of the member states, and that it violates the prohibition of monetary financing of the budget, the court said on its website.
The main “infringement” is that sterilization, a conservative policy measure used to stabilize the euro during the crisis - once abolished, could pump nearly $237 billion (175 billion euro) into the economy, Reuters reports. This would bring calm to euro zone currency markets.Read the full story here.

Tuesday, January 28, 2014

"The Great Bank Robbery" - Germany's Bundesbank calls for capital levy on the citizens to avert government bankruptcies.


"The Great Bank Robbery" - Germany's Bundesbank calls for capital levy on the citizens to avert government bankruptcies.(Reuters).

Germany's Bundesbank said on Monday that countries about to go bankrupt should draw on the private wealth of their citizens through a one-off capital levy before asking other states for help.

The Bundesbank's tough stance comes after years of euro zone crisis that saw five government bailouts. There have also bond market interventions by the European Central Bank in, for example, Italy where households' average net wealth is higher than in Germany.

"(A capital levy) corresponds to the principle of national responsibility, according to which tax payers are responsible for their government's obligations before solidarity of other states is required," the Bundesbank said in its monthly report.

It warned that such a levy carried significant risks and its implementation would not be easy, adding it should only be considered in absolute exceptional cases, for example to avert a looming sovereign insolvency.

The International Monetary Fund discussed the option in a report in October and said that reducing debt ratios to end-2007 levels for a sample of 15 euro area countries, a tax rate of about 10 percent on households with positive net wealth would be required.Read the full story here.

Friday, January 3, 2014

IMF paper warns of 'savings tax' and mass write-offs as West's debt hits 200-year high


IMF paper warns of 'savings tax' and mass write-offs as West's debt hits 200-year high. HT: The Telegraph


Much of the Western world will require defaults, a savings tax and higher inflation to clear the way for recovery as debt levels reach a 200-year high, according to a new report by the International Monetary Fund.


The IMF working paper said debt burdens in developed nations have become extreme by any historical measure and will require a wave of haircuts, either negotiated 1930s-style write-offs or the standard mix of measures used by the IMF in its “toolkit” for emerging market blow-ups.

The size of the problem suggests that restructurings will be needed, for example, in the periphery of Europe, far beyond anything discussed in public to this point,” said the paper, by Harvard professors Carmen Reinhart and Kenneth Rogoff.

The paper said policy elites in the West are still clinging to the illusion that rich countries are different from poorer regions and can therefore chip away at their debts with a blend of austerity cuts, growth, and tinkering (“forbearance”).Critics says extreme austerity without offsetting monetary stimulus is the chief reason why debts have been spiralling upwards even faster in parts of Southern Europe.Read the full story here

Friday, October 25, 2013

EU Leaders To Set Tight Timetable On Completing EURO BANKING UNION.


EU Leaders To Set Tight Timetable On Completing EURO BANKING UNION.(Reuters).

* EU wants agreement on bank resolution by end-year

* Wants plan on rewarding reforms by December

* Reforms seen key for sustainable growth in Europe

BRUSSELS – European leaders will confirm on Friday an ambitious timetable for the completion of a banking union, Europe’s biggest project since the euro, and set a December deadline for fleshing out the idea of rewards for structural reforms in the euro zone.Policy-makers believe a banking union in the 18 countries that will share the euro from next year will help increase the flow of credit, boost growth and help prevent financial crises in the future.

Under the union, the European Central Bank will directly supervise the euro zone’s 130 biggest banks from November 2014 and have the power to take over supervision of any of the smaller banks if needed.

Such a Single Supervision Mechanism is to be accompanied by a Single Resolution Mechanism (SRM) – a yet-to-be-created euro zone authority with its own fund that would decide how to wind down or restructure banks that are no longer viable.

As an intermediate step towards the SRM, the euro zone wants to agree on a Bank Resolution and Recovery Directive (BRRD), under which national authorities would coordinate their actions to deal with cross-border bank failures.

Euro zone finance ministers have already agreed what this intermediate law should look like, but they now need to reach a deal on the details of the legislation with the European Parliament.

European leaders meeting in the European Council will urge the parliament on Friday to adopt the BRRD and the Deposit Guarantee Directive by the end of the year, draft conclusions of their meeting, seen by Reuters, showed.

The leaders will also set an end-year deadline for euro zone ministers to move on to the next step, by agreeing on how they want the SRM to work, according to the draft conclusions.

That common position on the SRM would also have to go through the European Parliament – and time is short because the last parliamentary session before elections is in mid-April.

The European Council “underlines the commitment to reach a general approach by the Council (of ministers) on the Commission’s proposal for a Single Resolution Mechanism by the end of the year in order to allow for its adoption before the end of the current legislative period,” the conclusions said.

The European Commission, the EU executive arm, has proposed that it should be the single resolution authority – an idea that Germany opposes.

TESTS, BACKSTOPS, REFORMS AND REWARDS

Meeting all the deadlines appears ambitious, but it would allow the single resolution authority and its fund, which is to be financed from contributions from the banking sector, to become operational in early 2015 – an date favoured by the ECB.

Before the ECB takes over its supervisory duties, it wants to check all the banks’ financial health, by estimating the value of their assets under various adverse scenarios.

Because policy-makers expect the ECB check to show that some banks need more capital, EU leaders will reiterate that governments should be prepared to help if a bank cannot raise additional funds from the market.

Member states should make all appropriate arrangements, including national backstops, applying state aid rules,” the draft conclusions said.

EU leaders also want to flesh out in December a plan for euro zone countries to sign contracts with European institutions, promising to bring in reforms to make their economies more stable. Under the scheme, countries would get money if they deliver.

“Work will be carried forward to strengthen economic policy coordination, including by agreeing in December on the main features of contractual arrangements and of associated solidarity mechanisms,” the draft conclusions said.

Some policy-makers are sceptical about such contracts, mainly because no money has yet been set aside for “solidarity mechanism”.

Cash-strapped governments would be reluctant to create a new fund of a meaningful size on top of their existing commitments to the EU-wide long-term budget.

These contractual arrangements are extremely unattractive because they are either not possible to finance or they are a bit condescending – it is a bit like telling the kids what to do and then giving them some pocket money,” one senior policy-maker said.

Related:

Hmmm....Is Luxemburg next? Luxembourg Warns of Investor Flight from Europe

Friday, September 6, 2013

"Euro heist II" - Poland Confiscates Half Of Private Pension Funds To Cut Sovereign Debt Load.


"Euro heist II" - Poland Confiscates Half Of Private Pension Funds To Cut Sovereign Debt Load.HT: ZeroHedge.

While the world was glued to the developments in the Mediterranean in the past week, Poland took a page straight out of Rahm Emanuel’s playbook and in order to not let a crisis go to waste, announced quietly that it would transfer to the state – i.e., confiscate – the bulk of assets owned by the country’s private pension funds (many of them owned by such foreign firms as PIMCO parent Allianz, AXA, Generali, ING and Aviva), without offering any compensation. In effect, the state just nationalized roughly half of the private sector pension fund assets, although it had a more politically correct name for it: pension overhaul.

By way of background, Poland has a hybrid pension system: as Reuters explains, mandatory contributions are made into both the state pension vehicle, known as ZUS, and the private funds, which are collectively known by the Polish acronym OFE. Bonds make up roughly half the private funds’ portfolios, with the rest company stocks.
And while a change to state-pension funds was long awaited – an overhaul if you will – nobody expected that this would entail a literal pillage of private sector assets.
On Wednesday, Prime Minister Donald Tusk said private funds within the state-guaranteed system would have their bond holdings transferred to a state pension vehicle, but keep their equity holdings. The funds would effectively be left with only the equities portions of their assets, even this would be depleted, and there will be uncertainty about the number of new savers joining.
But why is Poland engaging in behavior that will ultimately be disastrous to future capital allocation in non-public pension funds (the type that can at least on paper generate some returns as opposed to “public” funds which are guaranteed to lose)?
 After all, this is a last ditch step which no rational person would engage in unless there were no other option. Simple: there were no other option, and the driver is the same reason the world everywhere else is broke too – too much debt.
By shifting some assets from the private funds into ZUS, the government can book those assets on the state balance sheet to offset public debt, giving it more scope to borrow and spend. Finance Minister Jacek Rostowski said the changes will reduce public debt by about eight percent of GDP. This in turn, he said, would allow the lowering of two thresholds that deter the government from allowing debt to raise over 50 percent, and then 55 percent, of GDP. Public debt last year stood at 52.7 percent of GDP, according to the government’s own calculations.
To summarize:
  1. Government has too much debt to issue more debt
  2. Government nationalizes private pension funds making their debt holdings an “asset” and commingles with other public assets
  3. New confiscated assets net out sovereign debt liability, lowering the debt/GDP ratio
  4. Debt/GDP drops below threshold, government can issue more sovereign debt
And of course, once Poland borrows like a drunken sailor using the new window of opportunity, and maxes out its new and improved limits, it will have no choice but to confiscate more assets, and to make its balance sheet appear better, until one day, there is nothing left in the private sector to confiscate. At that point the limit itself will have to be legislated away, and Poland will simply continue borrowing until one day there are no foreign lenders willing to take the same risk as the nation’s private pensioners. At that point, Poland, which is in the EU but still has the Zloty, can just go ahead and monetize its own debt by printing unlimited amounts of its currency.
Of course, we all know how that story ends.
The response to the confiscation was, naturally, one of shock:
The reform is “a decimation of the …(private pension fund) system to open up fiscal space for an easier life now for the government,” said Peter Attard Montalto of Nomura. “The government has an odd definition of private property given it claims this is not nationalisation.”
“This is worse than many on the markets had feared,” a manager at one of the leading pension funds, who asked not to be identified, told Reuters.
“The devil is in the detail and we don’t yet know a lot about the mechanism of these changes, what benchmarks will be use to evaluate our performance… (It) looks like pension funds will lose a lot of flexibility in what they can invest.”
Catastrophic consequences for fund flows aside, the Polish prime minister had a prompt canned response:
Tusk said people joining the pension system in the future would not be obliged to pay into the private part of the system. Depending on the finer points, this could mean still fewer assets in the private funds.
“The (current) system has turned out to be built in part on rising public debt and turned out to be a very costly system,” Tusk told a news conference.
We believe that, apart from the positive consequence of this decision for public debt, pensions will also be safer.
You see, he is from the government, and he is confiscating the pensions to make them safer. Confiscation is Safety and all that…
Polish officials have tried to reassure investors, saying the overhaul avoids the more radical options of taking both bond and equity assets away from the private funds outright.
They say the old system effectively made Polish public debt appear higher than it really is.
Well, once you nationalize private assets, the public debt will lindeed appear lower than it was before confiscation: we give them that much.
End result: “The Polish pension funds’ organisation said the changes may be unconstitutional because the government is taking private assets away from them without offering any compensation…. This may lead to the private pension systems shutting down,” said Rafal Benecki of ING Bank Slaski.
Unconstitutional? What’s that. But whatever it is, it’s ok – after all the public pension system is still around. At least until that too is plundered. But in the meantime, all such pensions will be “safer”, guaranteed.
But best of all, in the aftermath of Cyprus, we now know what the two most recent European blueprints for preserving the myth of solvency are: bail-ins, which confiscate deposits, and pension fund “overhauls”, which confiscate, well, pension funds.
And now, back to the global recovery soap opera.

Tuesday, August 20, 2013

CREDIT SUISSE: The End Of Zero Interest Rates May Create A 'Huge Financial Disruption Akin To The End Of A War.


CREDIT SUISSE: The End Of Zero Interest Rates May Create A 'Huge Financial Disruption Akin To The End Of A War.HT:Business Insider
It wasn’t so long ago that the challenge of making money with interest rates stuck around zero was investors’ top concern. Those days are gone. Today, they’re worried about the opposite: the threat that now-rising rates pose for fixed income investments. That, and the downturn in emerging markets that many only recently embraced in the hunt for yield caused by those near-zero rates.
It’s easy to identify the date that things changed: May 22, the day that the Federal Reserve first alerted markets that it might soon start “tapering” the $85 billion in monthly asset purchases it has been making since December to juice the economy. And soon looks to be getting even sooner. A steady improvement in U.S. employment figures—unemployment fell from 7.6 percent in June to 7.4 percent in July—has brought into focus the 6.5 percent unemployment target the Fed set as a prerequisite for raising short-term interest rates. On Thursday, the U.S. Bureau of Labor Statistics released yet another piece of good news on the employment front: New applications for unemployment benefits sank to their lowest levels in six years in July.
That’s great news for Americans who happen to be landing new jobs, but not as pleasant for bond investors worried about rising rates. The employment data, as well as news that inflation rose significantly in July (another potential trigger for the Fed to tighten monetary policy) led investors to dump U.S. Treasuries Thursday, pushing yields to a two-year high. The yield on a 10-year Treasury bond has topped 2.8 percent, about 60 percent higher than at the beginning of the year.
Now that yields have started climbing, investors should expect that improving economic momentum will keep them moving higher – and that will have serious implications for investors in the world’s three largest economies: European Union, Japan and the United States.
“In our view, the potential end of near-zero interest rates is exactly the type of event that can trigger enormous changes in asset prices and capital flows within and across economies,” Credit Suisse’s fixed income strategy team explained in a note this week called ”Zero Isn’t Forever.” “This can create a huge financial disruption akin to the end of a war.”
This particular “war” is ending later than it should have, the team wrote, arguing that long-term interest rates have remained low far longer than the data warranted. Rates in the G3 started falling in mid-2011, when the European crisis was at its worst. But industrial production momentum, a key indicator of global economic activity, started looking more solid as early as last November. Add to that the steady recovery in the U.S. labor market and the receding threat of a breakup of the euro zone since European Central Bank President Mario Draghi’s July 2012 pledge to take any measures necessary to hold the monetary union together, and one would have thought rates would have been climbing some six months before the Fed caused such pandemonium in May. So why didn’t they? Because the major central banks continued easing in the face of that good news, that’s why. 
And why would they do that? Because they were more focused on falling inflation, despite the fact that inflation is a lagging indicator. (If it’s not one thing, it’s another.) The recent jump in long-term rates, then, is simply an overdue correction. “We think long-term interest rates were significantly mispriced even before tapering talk began,” the strategists wrote.
The uptick in industrial production momentum around the world, which tends to track quite closely with long-term bond yields, is still going strong, and the analysts expect it to continue putting upward pressure on rates. Global industrial production momentum went from -1 percent in November to 4.1 percent in May, and the strategists expect it to hit 7 percent by the end of this year, as both Europe’s painful recession and China’s significant slowdown appear to be flattening out.Read the full story here.

Sunday, August 11, 2013

Eurozone Funding Shortfall Rises To Over $4 Trillion, Increases By More Than $500 Billion In A Year...But wait Europe has a Plan.


Eurozone Funding Shortfall Rises To Over $4 Trillion, Increases By More Than $500 Billion In A Year...But wait Europe has a Plan.HT: ZeroHedge; Hat4uk.

Back in April 2012, Zero Hedge pointed out something rather disturbing for the European banking sector and defenders of the European monetary myth: the "aggregate shortfall of required stable funding Is €2.78 trillion" which was the number estimated by the BIS' Basel III rules needed to return to some semblance of balance sheet stability in Europe. More importantly, this was a number so big, it was obvious that there was only one way to deal with it: cover it up deeply under the rug and pray it never reemerged.
What happened next was inevitable: Basel III's implementation was delayed as there was no way Europe's banks could satisfy their deleveraging requirements, while the actual capital shortfall hole became bigger and bigger. Today, 16 months later, the FT discovers what Zero Hedge readers knew long ago in "Eurozone banks need to shed €3.2tn in assets to meet Basel III." In other words, not only has Europe not fixed anything in the past year, but the liquidity tsunami injected by the central banks merely taped over the epic capital shortfall that just got epic-er, increasing from €2.8 trillion to €3.2 trillion, an increase of over half a billion to over $4 trillion in one short year.
Sadly, just like back in April 2012, so now, Europe has no hope of actually addressing this much needed deleveraging and so the can kicking will continue until the number rises to $5 trillion, $6, $7 etc until one day the market's "head in the sand" strategy finally fails and every emperor around the world is found to be naked.
From the FT:
Europe’s biggest banks will have to cut €661bn of assets and generate €47bn of fresh capital over the next five years to comply with forthcoming regulations aimed at reducing the likelihood of another taxpayer funded bailout.
The figures form part of an analysis by the UK’s Royal Bank of Scotland – which singles out Deutsche Bank, Crédit Agricole and Barclays as the banks most in need of fresh capital – highlighting that five years on since the financial crisis, Europe’s banks are still “too big to fail”.
Overall, the region’s banks need to shed €3.2tn in assets by 2018 to comply with Basel III regulations on capital and leverage, according to RBS.
The burden is greatest on smaller banks, which need to shed €2.6tn from their balance sheets, raising fears that lending to the region’s small and medium size enterprises will be sharply reduced as a result.
“There is too much debt still across Europe’s economies and the manifestation of that is on bank balance sheets,” said James Chappell, an analyst at Berenberg bank. “The major issue is that the banks still don’t have enough capital to write down those loans.”
Eurozone banks have already shrunk their balance sheets by €2.9tn since May 2012 – by renewing fewer loans, repurchase and derivatives contracts and selling non-core businesses – according to data from the Frankfurt-based European Central Bank.
Deutsche Bank recently said it would seek to cut its assets by about a fifth over the next two and a half years. Barclays, which announced a £5.8bn rights issue last month, said it wants to shrink its balance sheet by £65bn-£80bn.
Europe’s banking sector assets are worth €32tn, or more than three times the single currency zone’s annual gross domestic product.
Of course, if Europe's banking sector actually does take its deleveraging obligations seriously, what will happen to Europe's economy, where private sector loan creation is already at a record low level, will be nothing short of a stunning contraction, unlike anything seen in the past 5 years. And yet, that is precisely the path Europe most take in order to emerge on the other side with a healthy beating financial heart. That it won't is a given because doing the right thing would mean a complete wipe out for the banker oligarchy. And, as always, it will be the common man who will suffer when the forced deleveraging day finally comes.

The PLAN:

 Revealed: official details on how the EU will steal from us.

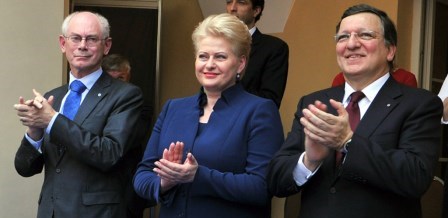
Three beaming eurocrats – Barroso, Van Rompuy and Lithuanian Dalia Grybauskaite – emerged triumphant from a session two days ago, in which they mapped out the biggest bank heist in world history. This is to put flesh on the eurozone law hastily passed on August 1st (while EU citizens were on holiday) to deal with the inevitability event of a bank collapse. Under this draft proposal – which many expect to be applied to the entire EU – no depositor big or small will in future be able to feel safe with money deposited in a bank. The Slog now calls for those who represent us, across the entire cultural spectrum of European society – to do something.
In a barely read piece a month ago, the International Business Times reported on the rapidly drafted new EU law for “overhauling its policy on how banks receive bumper bailouts”. Be aware: this is an EU move, not a eurozone move: it is already law (it passed on August 1st) and although for now it applies only to the eurozone, it is an EU law. Hardly anyone has commented on this, but the approach being taken matches word for word the 3-card trick George Osborne used six weeks ago when he said:
In future, taxpayers will not be called upon to bail banks out. It will be down to the creditors and the owners”.
The most remarkable example of double-speak to date, at the time I pointed out that creditors are taxpayers (they’re account holders, simple as that) and so as the Establishments daren’t ask us for higher taxes to bail out their mates in the banking system, they will take it via, if you like, Direct Debit. It is exactly the same principle of stealing the Troika wishes to apply to Greek private pension funds.
The initial piece at the IBT website noted that ‘Eurozone leaders agreed upon the major policy shift and also confirmed that the new rules will help protect the taxpayer and move the burden of bailing out the banks onto shareholders and junior debt holders.” Again, more bollocks: how will ripping your money out protect you? And note – junior debt holders…aka, you and I.

But yesterday from the German site Deutsche Wirtschafts Nachrichten (German Economic News) came a piece reporting that all bets are off as far as the ‘guarantee of all funds under €100,000′ pledge is concerned. Under the current Lithuanian Presidency of Dalia Grybauskaite (seen left between a Trot and a poet), the proposal as drafted – and almost entirely ignored by the Western media – states as follows:
* Treatment will not be the same regardless of size of deposit, BUT small account holders will have to wait up to four weeks to get their money….’depending on how serious the insolvency is’. During that time, there will be a maximum withdrawal of €100-200 per day – again, perhaps less depending on the seriousness of the failure. (Based on the Cyprus experience, the haircut in the end will be at least 60%).
* The EU Parliament – allegedly – is demanding that deposits of €100,000+ euros should be confiscated within five days. (So much for MEPs offering us some kind of protection from the Sprouts).
* In the event of a banking collapse, all previous government commitments are null and void.  The force majeur of “exceptional circumstances” can lead to ways round such pledges. Part of the new plan suggests savers could also be subject to a ‘penalty tax’ if they have less than € 100,000 in the bank. (So much for Merkel’s promise to the German people).
George Orwell could’ve dropped acid and still not come up with a scheme quite so assumptive and brazenly deranged as this one. It is based on the following insane principles:
1. Putting money in a bank makes every citizen a creditor of that bank, equally prone to confiscation in order to repay….who exactly? The answer is, other banks it owed money. So it’s not really our money after all, it’s the banking sector’s money. After it’s been taxed by the Government, despite the fact that we earned it…it’s really all bankers’ money after all. Unbelievable.
2. If we are prudent enough to keep money in smaller amounts in lots of accounts, we will have to pay a ‘penalty tax’ – well of course we will: I mean, given it’s never our money really – we’re just borrowing it, or something – then quite right too. And because it isn’t really our money, we shall be given strictly limited spending money per day. The brass neck is beyond belief.
3. If you have been seditious enough in your life to actually make quite a lot of money legally, then within five days the money that was never really yours will be taken back by its rightful owners…the bankers….or the Government rescuing the bankers but without doing it in our taxes. Why five days – why not five seconds? I mean, it’s their money: we were just earning it for safe keeping, right? Of course we were.
4. Anything is an exceptional circumstance if they say it is. Even the Nazis in 1933 had to burn down the bloody Reichstag to declare a State of Emergency. In 2013, it requires just one dumb, over-leveraged, f**kwitted bank to collapse under the weight of its CEO’s ego, and we’re all pauperised by Law.
This is no longer a political issue. This is a case of one simple rule by which decent citizens must abide: stealing things is wrong…especially when it’s done to repair your own stupid decisions in the past.

Tuesday, July 2, 2013

Cyprus ‘defaulted’ on debt – Moody’s.


Cyprus ‘defaulted’ on debt – Moody’s.HT: RussiaToday.

The downgrade, although Moody's doesn't technically have a default rating, was issued after Cyprus said it would delay the bonds and go ahead with a bond swap default strategy.
Cypriot authorities said they will swap government bonds maturing in 2013 through to the first quarter of 2016 with new debt that matures at between five and 10 years.
The bond swap is a ‘distressed exchange’, and therefore, a debt default. Because the amount exchanged is less than the original deal, and Cyprus is allowed to avoid payment on the bonds.
Cyprus' biggest banks are the largest holders of Greek bonds, which became ‘bad’ and ‘distressed’ following the Greece financial crisis, which left Cypriot banks with big debts.
67 percent of outstanding amounts were subject to the swap.
Moody's said the exchange of Cyprus government bonds for new ones with a longer maturity level means the financial commitment of Cyprus to the holders of the bonds will decline.
Moody’s statement on Monday came after Standard and Poor’s downgraded Cyprus to ‘selective default’ and Fitch downgraded the rating to ‘restricted default’ because of the debt exchange.
Other factors, including the likelihood that Cyprus will comply with the rest of the measures spelled out in its bailout agreement with the International Monetary Fund, the European Central Bank and the European Union, will be taken into consideration as well.
The island’s sovereign credit rating was downgraded from B3 to Caa3, or junk status, in April, shortly after the country’s accruement of 10 billion euros in loans from European lenders.
Economic activity on the island remains dormant, unemployment high, and bank deposits have dispersed since the deal.
In exchange, the financial center agreed to cut spending and restructure its banking system.
Moody’s say it will reissue a credit rating for Cyprus ‘in due course’ in which they will reassess the impact of the bond exchange on the Cypriot economy.
The next credit rating will also closely look at Cyprus’s ability to carry out compliance measures under its lenders as well as potential growth prospects.
Cyprus' bailout problems are heavily tied to Greece as Cyprus' biggest banks are the largest holders of Greek bonds. Greece had huge financial problems which has left Cyprus' banks with big debts.

In related news: Greece Has Three Days To Deliver On IMF Terms Or Face Consequences 

Thursday, June 27, 2013

"The Great Euro Bank Robbery" - Investors to pay for bank failures – EU.


"The Great Euro Bank Robbery" - Investors to pay for bank failures – EU. HT: RussiaToday.
If pursued, bailout strategy, shareholders, bondholders and depositors with more than 100,000 euro will share the financial strain of saving a bank. Deposits under 100,000 will be protected.
Under the new protocol, which would come into effect in 2018, countries would be obliged to absorb 8 percent of a bank’s liabilities, with some leeway thereafter.
The next time a big bank fails, governments will make sure “that shareholders and creditors are liable first and foremost,” German Finance Minister Wolfgang Schaeuble told reporters.

Rescuing banks will not be less painful for political leaders and institutions, who can now just take bank deposits instead of hiking taxes.
French Finance Minister Pierre Moscovici said France got “what we wanted” from the blueprint, and Danish Economy Minister Margrethe Vestager called the deal a “balanced compromise.”
The Irish, whose taxpayers paid nearly $40 billion to bail out Anglo Irish Bank, are happy that the new status quo will be bail-ins, not bail-outs. Banks will have to bail themselves out.
Other ministers were happy to have a universal strategy to address dealing with troubled banks."If a bank gets in trouble we will now, throughout Europe, have one set of rules on who pays the bill," Dutch Finance Minister Jeroen Dijsselbloem said.
Germany has previously indicated it disagrees with a universal plan to deal with bailouts across the continent, and has warned having such a strong central banking authority goes against standing treaties.
“It took a long time and it was arduous and it was intense,” German Finance Minister Wolfgang Schaeuble said, without publicly voicing Germany’s previous qualms over the structure.
It is highly unlikely Chancellor Merkel will agree to such a banking union before the election in September.
The European Central Bank will officially take over supervision of eurozone banks next year. Last year it provided 1 trillion euros of cheap three-year loans to struggling banks.
Under the new umbrella, banks will be able to receive direct loans from the European Stability Mechanism, a eurozone bailout fund. The European Banking Authority was set up in 2011 to integrate rules across the EU and has secured a new supervisory function. All 17 currency member states support the motion, but some fear an all-too-powerful central bank.
By next week, the 27 member states need to choose a governing body, or executor, to carry out the task.
The legislature’s text grants nations a clear right to nationalize failing banks, if the step is seen as essential to preserve financial stability.
Switzerland, Norway, and other non-EU countries within Europe will still have jurisprudence over how to deal with bank failures.
The precedent was set after Cyprus requested an EU bailout and aid was dependent on the country’s agreement to levee account holders with more than 100,000 euro, which will likely result in a loss of 30 percent in savings.
The Cyprus scenario marked the first time depositors were forced to contribute to the bank’s bailout and now it is set to become the norm.Read the full story here.

Monday, May 6, 2013

German euro founder calls for 'catastrophic' currency to be broken up.


German euro founder calls for 'catastrophic' currency to be broken up.(Telegraph)."The economic situation is worsening from month to month, and unemployment has reached a level that puts democratic structures ever more in doubt," he said.

"The Germans have not yet realised that southern Europe, including France, will be forced by their current misery to fight back against German hegemony sooner or later," he said, blaming much of the crisis on Germany's wage squeeze to gain export share.

Mr Lafontaine said on the parliamentary website of Germany's Left Party that Chancellor Angela Merkel will "awake from her self-righteous slumber" once the countries in trouble unite to force a change in crisis policy at Germany's expense.

His prediction appeared confirmed as French finance minister Pierre Moscovici yesterday proclaimed the end of austerity and a triumph of French policy, risking further damage to the tattered relations between Paris and Berlin.

"Austerity is finished. This is a decisive turn in the history of the EU project since the euro," he told French TV. "We're seeing the end of austerity dogma. It's a victory of the French point of view."

Mr Moscovici's comments follow a deal with Brussels to give France and Spain two extra years to meet a deficit target of 3pc of GDP. The triumphalist tone may enrage hard-liners in Berlin and confirm fears that concessions will lead to a slippery slope towards fiscal chaos.

German Vice-Chancellor Philipp Rösler lashed out at the European Commission over the weekend, calling it "irresponsible" for undermining the belt-tightening agenda.

Mr Lafontaine said he backed EMU but no longer believes it is sustainable. "Hopes that the creation of the euro would force rational economic behaviour on all sides were in vain," he said, adding that the policy of forcing Spain, Portugal, and Greece to carry out internal devaluations was a "catastrophe". Read the full story here.

Wednesday, May 1, 2013

Video - Nigel Farage On “Wholesale, Violent Revolution” In Europe - “Get your money out,”


In a little under two minutes, Nigel Farage sums up the utter farce that “the religion” that Europe has become.

He explains, his fear is that what will break up the Euro, “is not the economics of it, but wholesale, violent revolution,” in the Mediterranean, and that is “all so unnecessary!”

Speaking at Simon Black’s Offshore Tactics workshop, the so-called modern day Cicero goes on to point out that France’s Hollande is “the number 1 among idiots running countries around the world,”and worries that Merkel’s pending election means there will be more and more ‘tough talk and action’ as she shows the people she is in charge.

Simply put he warns, alongside Ron Paul, that if you have money in European banks, “Get your money out,” because, “when the next phase of the disaster comes, they will come for you.”HT: ZeroHedge.

Sunday, April 28, 2013

"The Great Euro Bank Robbery" - Luxembourg Is Not The Next Cyprus, Not Yet, But....


"The Great Euro Bank Robbery" - Luxembourg Is Not The Next Cyprus, Not Yet, But....HT: The TestosteronPit.By WolfRichter.
The Grand Duchy of Luxembourg, with a population of just over half a million, smaller even than the other speck in the Eurozone, the Republic of Cyprus, ranks in the top three worldwide in per-capita GDP. In a Eurozone wealth survey, it had the highest average household wealth – €710,100. Only Cyprus, a former off-shore banking center in the Eurozone, came close. Yet Luxembourg is threatened with ruin.
It has 141 banks – bank companies, not ATMs. One bank per 3,808 people. Most of them do private banking. The financial sector added 38% to GDP in 2010 and contributed 30% to the country’s tax revenues, according to the Luxembourg Bankers’ Association (ABBL).
All due to bank secrecy and tax laws. But suddenly, after Cyprus had been massacred, Luxembourg buckled.
With the big German guns, and the smaller guns from other nations, swinging in its direction, Luxembourg agreed to participate in an international automatic data-sharing arrangement that would send banking data of foreign clients to their countries, starting in 2015. 
Prime Minister Jean-Claude Juncker, somewhat defensively, proclaimed that lifting bank secrecy wasn’t such a big deal, that Luxembourg didn’t live from tax evasion. For the banks, the “lights won’t go out in 2015,” he said.
During the entire Eurozone bailout debacle that he presided over until February as President of the Eurogroup, he’d proven to be time and again an inveterate optimist.
It’s expected that only 60 to 70 banks will survive in the coming years,” declared Alain Steichen, a prominent Luxembourgian tax lawyer, at a conference about the consequences of the data-sharing agreement. He should know. Per his online profile, he “assisted Thomson in the merger acquisition of Reuters in order to form Thomson Reuters, with the group’s main holding location being Luxembourg.” He also “assisted Chase Manhattan in the merger acquisition of JP Morgan in order to form their main holding company in Luxembourg.” Yup, there are a lot of benefits to doing business through Luxembourg.
Combine bank secrecy with nominee corporations to get a particularly juicy cocktail. An entire industry of “fiduciaries” has formed around the banks for that purpose. These accounting, audit, and law firms set up and maintain tax-advantaged nominee corporations, the infamous mailbox companies, whose directors and top executives are principals of the fiduciary firm. The client and the source of money remain anonymous to the outside world. A perfect setup for money laundering. Because the bank is doing business with a Luxembourg mailbox company, not a foreigner, and because the signatories are pillars of Luxembourg’s society, the setup is impervious to the automatic data-sharing arrangement. But now mailbox companies too are under attack, not only in Europe, but also in the US Congress.
I expect a serious change of the banking landscape because there will be customer withdrawals,” Alain Steichen explained. Some banks, he said, “would lose the critical mass needed to survive.
The private banks he was talking about managed €300 billion in assets, generated €3.14 billion in revenues, and contributed €503 million in taxes, according to the ABBL. They employ over 10,000 people directly and indirectly. Of the assets under management, 19% are from Luxembourg, the rest from other countries. Half of that system would disappear; the survivors would have to shrink.
A large part of the clients of the Luxembourgian banks have undeclared money,” Steichen pointed out. They wouldn’t have a lot of options other than closing their accounts in Luxembourg, he said. They might repatriate their funds – and pay fees, taxes, and penalties – or transfer their funds to Singapore, Monaco, or other murky banking centers. Either way, these assets would leave Luxembourg. Their power to generate income, jobs, and tax revenues would evaporate.
This “undeclared money” has been called “black money” in the battle over Cyprus, much of it from Russians. Northern Europe revolted against bailing out mailbox companies and their black-money bank accounts. While they were at it, Northern Europe, including France in this case, shut down the whole offshore machine, crippled the Cypriot economy, smashed its largest source of income and wealth, and demolished its business model. Encouraged by success, Northern Europe, now including the UK, swiveled its guns in direction of Luxembourg.
Luxembourg was horrified. There were too many parallels between it and Cyprus – the mailbox companies, foreign black money, a bloated financial sector, high household wealth.... It was the era of austerity when pensions, wages, and social services were on the chopping block in other countries. Taxes were being jacked up, as in France, to an absurd degree. Belts were being tightened around the poor. So, tax evasion by the rich and not so rich has become an obvious target. Governments would crack down, not on their own tax dodgers, but more conveniently on countries whose business it was to help them.
With 38% of GDP depending on the financial sector, Luxembourg could not risk a sudden “transition” to a new business model, à la Cyprus. Some of the banks could collapse in the process. It would cause a depression and shred the country’s wealth. Instead, Luxembourg would cooperate, in return for a gradual transition, some loopholes, and a little wiggle room, knowing that the good times were over, and that on the other end of the spectrum, there’d be the Cypriot scenario.
Austerity in Spain succeeded in trimming the bloated government sector. But instead of picking up the slack, the private sector destroyed jobs almost four times faster! The hope is that this fiasco will finally reverse course, that something will click and start a virtuous cycle before the unspeakable happens. But so far, it has relentlessly gotten worse. Read.... The Spanish Unemployment Powder Keg.


Flashback : MFS The Other News March 29Th.: Hmmm....Is Luxemburg next? Luxembourg Warns of Investor Flight from Europe.

Related: MFS on Wednesday 27 Th March : "The Great Euro Bank Robbery" - Hands off our finance sector, Luxembourg warns
Hmmmm.....As i wrote on Monday 25 Th March: Reading material Here:

Euroclear Bank is subject to effective regulation, supervision and oversight of the NBB and FSMA, but cooperation with the Luxembourg authorities should be improved.

The legal framework provides the Belgian authorities with sufficient powers to obtain timely information and induce change.
However, as Euroclear Bank is in competition with the Luxembourg based Clearstream Banking Luxembourg—which offers similar settlement and banking services–close cooperation with the Luxembourg authorities is needed to avoid any competition on risk management frameworks.

As both entities are highly relevant for the global financial stability the Belgian and Luxembourg authorities should evolve from the existing cooperation towards a cooperative framework that would allow them to take common decisions and implement these simultaneously in both entities.

The plans to include Euroclear Bank on the list of eligible banks for the SSM may further contribute to a level playing field.

77. The national securities depositories of Belgium, France, and the Netherlands, that share a common IT platform provided by the Euroclear Group, are subject to effective regulation, supervision, and oversight of the Belgian, Dutch, and French authorities, despite the fact that the legal frameworks differ substantially between the three countries. The cooperation between the different authorities is effective and contributes to the financial stability in Belgium, France, and the Netherlands. Crisis management frameworks are in place that are regularly tested and updated

Friday, April 26, 2013

"Eurogeddon" Germany rejects joint EU bank deposit scheme: Merkel.


"Eurogeddon" Germany rejects joint EU bank deposit scheme: Merkel.(HD).Germany rejects at least for now a standardized Europe-wide bank deposit guarantee scheme, Chancellor Angela Merkel said on yesterday. Germany, Europe’s largest economy, fears such a scheme would leave its taxpayers footing the bill for mistakes made by banks in other euro zone countries.

Speaking in the east German city of Dresden, Merkel also reiterated her centre-right government’s view that in the future bank shareholders should also suffer losses in the event of their institutions receiving euro zone rescue funds.

Wealthy depositors in Greek Cypriot banks were forced to take a hit as part of the recent international bailout for Greek Cyprus. Hmmm.....Place your bet....'rien ne vas plus.'Read the full story here.

Saturday, April 20, 2013

"The Great Swiss Bank Robbery" - Switzerland Revises 1934 Banking Act To Allow Bail-In Deposit Confiscations.


"The Great Swiss Bank Robbery" - Switzerland Revises 1934 Banking Act To Allow Bail-In Deposit Confiscations.(SilverDoctors).

The Swiss Financial Market Supervisory Authority (FINMA) has quietly joined the growing parade of western nations who have quietly re-written banking laws to allow depositor bail-ins upon the next banking crisis.
If Switzerland, the once ultimate safe haven for banking deposits across the world is preparing to confiscate depositors funds, there truly is no protection anywhere other than physical gold and silver in your own possession!
In the event that a bank is failing or where its capitalization is no longer adequate, the Swiss Financial Market Supervisory Authority (“FINMA”) may take measures to improve such bank’s financial viability rather than liquidating it. “Loss absorption” and “bail-in” are important instruments to support any such measures.
The Swiss document begins by advising that the FINMA now has legal authority to confiscate depositor funds, thanks to a revision of the Banking Act of 1934, completed in 2011, as well as the revision of the Bank Insolvency Ordinance completed Nov 1st 2012:
In the event that a bank is failing or where its capitalization is no longer adequate, the Swiss Financial Market
Supervisory Authority (“FINMA”) may take measures to improve such bank’s financial viability rather than
liquidating it. “Loss absorption” and “bail-in” are important instruments to support any such measures. This
is now possible as a result of a revision of the Banking Act of 8 November 1934 (the “Banking Act”) in 2011 and
the taking effect of a revised Bank Insolvency Ordinance on 1 November 2012 (the “Bank Insolvency Ordinance”)
and of a revised Capital Adequacy Ordinance on 1 January 2013 (the “Capital Adequacy Ordinance”).

The document states that The Banking Act now grants discretion to FINMA regarding depositor bail-in measures:
RELEVANT PROCEEDINGS Under the Banking Act, if there are concerns that a bank is
over-indebted or if a bank does not meet liquidity or regulatory capital requirements, the FINMA may as appropriate: (i) take protective measures; (ii) initiate bank reorganization
proceedings; or (iii) order the liquidation of the bank (bankruptcy). The Banking Act grants significant discretion to FINMA in this context. This includes, inter alia, ordering
a bank moratorium, a maturity postponement or “bail-in” measures.
And in the scope of bail-in measures, states that bail-ins are to be a measure of last resort (translation: we’ll make this sound unlikely until the banks lose their first franc):
BAIL-IN MEASURES
4.1 Scope
The loss absorption measures described above relate to capital instruments issued by the bank. In addition, the revised procedural rules as specified in the secondary legislation to the Banking Act applicable in a bank reorganization context (i.e. if FINMA believes that the bank may be successfully reorganized or if at least part of the business of the failing bank may be continued), as enacted by FINMA, provide for the competence of FINMA to convert or write-off other
debt (even in the absence of any contractual provision to that effect in the arrangement governing such debt) if and to the extent necessary to allow the bank to meet its regulatorycapital requirements after completion of the reorganization(“bail-in”).
Such bail-in is designed to be available as a measure of “last resort” to be taken in the event that the loss absorption under the capital instruments issued by the bank is not sufficient to restore the required capitalization of the failing bank and if the creditors are likely to be better off than in an immediate insolvency of the bank.The bail-in must be specified in the reorganization plan, which must be approved by FINMA and – except for banks of systemic importance – also by a majority of non-privileged creditors (calculated on the basis of the claim
amounts). If such approval cannot be obtained, the bank would be liquidated in bankruptcy proceedings. In the event that FINMA only applies protective measures, but does not consider any reorganization measures as necessary or adequate, a bail-in could not occur as one of such
protective measures.
Hmmm....Who needs banks with robbers like these guys?Read the full story here.
Related Posts Plugin for WordPress, Blogger...